
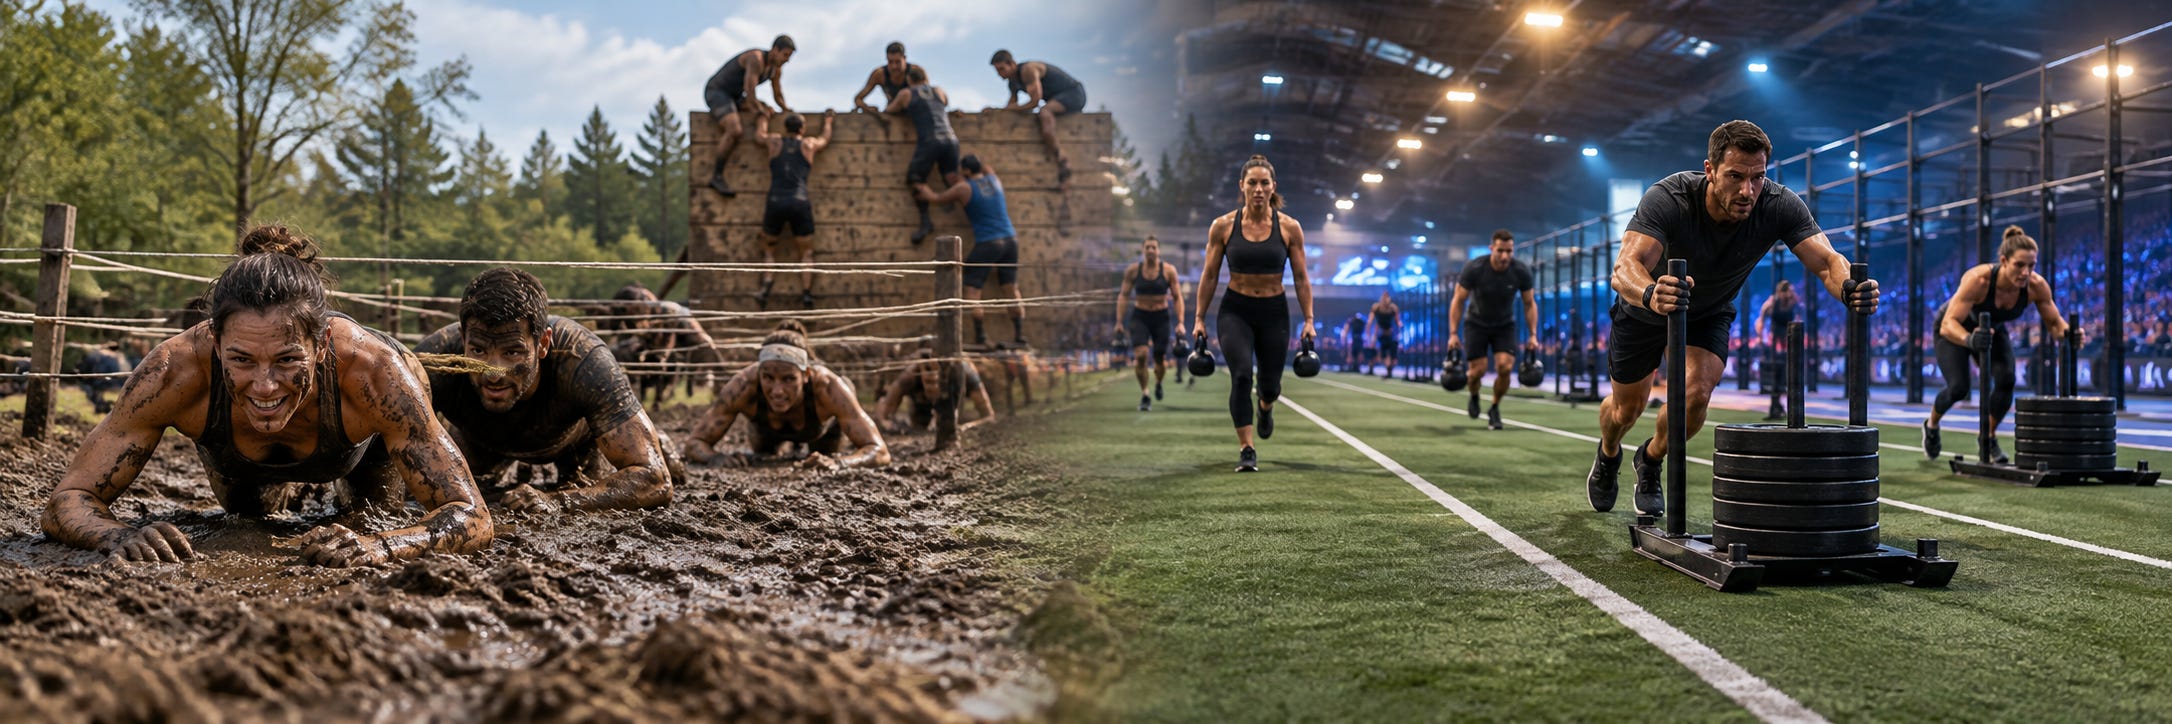
The current wave of fitness racing feels familiar. The mud has largely been replaced by indoor venues, sleds and workout stations. Footwear companies are competing for position, new formats are expanding, and investors see an opportunity to build something bigger than an event calendar.
Muddy Buddy, Tough Mudder, Spartan and Rugged Maniac are brands from the OCR event world that offered a different way to challenge yourself, bring friends along and leave with a story. They helped turn physical effort into something people would pay for, train for, and identify with.
There is real opportunity in the new wave of fitness racing, but there is also a tendency to confuse a growing category with a collection of durable businesses.
Being first, getting funded, and lasting are different accomplishments
Bob Babbitt started Muddy Buddy in 1999, more than a decade before the 2010 launches of Tough Mudder, Spartan and Rugged Maniac. Its partner-based run-and-bike format helped introduce people to the kind of shared physical challenge that would become a much larger business. Being early, however, did not make it the enduring national platform.
I was at Competitor Group, and I believe we missed the opportunity. In my opinion, we did Muddy Buddy a disservice by not adapting as the market evolved. We could not get past the bike component, even as it complicated event operations and the participant experience. We allowed that constraint to limit participation, growth, and the resources we were willing to put behind the event.
The lesson, for me, is not that Muddy Buddy lacked potential. It is that we became too attached to one part of the format rather than protecting what made the experience valuable: two people taking on a challenge together.
Tough Mudder built a recognizable brand around teamwork and overcoming obstacles. The brand survived, but the independent business did not. Spartan acquired it through a bankruptcy settlement in 2020.
Rugged Maniac followed another path. In 2018, New Media Investment Group bought a controlling stake in its parent company, Rugged Races. Six years later, Rugged Maniac shut down and canceled its entire 2024 schedule.
That history sets the table for assessing the latest expansion announcement or investment round.
A successful transaction does not guarantee a lasting event. A surviving brand does not necessarily mean the original company survived. And consolidation does not require every acquired brand to disappear.
Spartan and Tough Mudder continued as distinct offerings under the same ownership umbrella. There was value in preserving different reasons for people to participate.
That may be a better guide to the future of fitness racing than a prediction that one format will take everything.
The field is growing, but the ownership picture is already connecting
ATHX has announced plans to enter six U.S. markets in 2027: San Diego, Las Vegas, Denver, Nashville, New York and Chicago. Its projected schedule includes approximately 80,000 athletes across 45 events in more than 18 countries. Those are expansion targets, not participation proof of concept.
The format offers a different proposition from HYROX. ATHX combines strength, endurance, and metabolic conditioning across a 2.5-hour competition. HYROX gives athletes the same basic test each time: eight one-kilometer runs alternating with eight workout stations.
XENOM brings a different approach, positioned as a decathlon of fitness with 10 standardized events over two days.
But the most interesting development is not simply the arrival of another competitor. HYROX founders Christian Toetzke and Moritz Fürste have invested in XENOM and joined its board. The businesses also announced a strategic partnership covering marketing, event activation, and education.
That complicates the idea of four independent formats fighting for one customer.
The founders of one platform are backing another. My read is that they see room for different competitive experiences, with commercial value in connecting them.
Those relationships are a significant signal to track. The category currently has room for several brands without supporting the same number of independent businesses.
The relationship between events matters more than the event itself
For me, the central question is retention.
Who gets someone beyond “I tried it” and gives them something they want to train for year after year?
That is where CrossFit belongs in a different part of this conversation.
CrossFit is not simply a competition series. Its business includes a training methodology, coach education, and affiliate licensing. The Games sit within a broader system of independently owned gyms and daily participation.
The event is not the only point of contact. The relationship can exist every morning, with the same coach, the same training partners, and the same place in someone’s routine.
That does not insulate the corporate business from ownership challenges. CrossFit announced in 2025 that it was seeking a new owner. It does, however, show why we should distinguish the strength of a community from the circumstances of the company behind it.
ATHX is also developing an affiliate-gym program, connecting its competition to training communities between events.
That is an important part of the model. A race gives people a date on the calendar. The training around it can give them months of purpose and connection.
If I were evaluating one of these businesses, I would want to understand that relationship before getting too excited about its next ten cities. How many athletes return? How many bring someone with them? How much participation comes through coaches and gyms rather than another round of paid acquisition?
A full first event is encouraging. A second event filled with returning customers is the start of a business.
Standardization is an advantage, not a complete strategy
Look at running. The 5K, 10K, half marathon and marathon give the sport a set of recognized distances that work across markets, organizers and generations of participants. The half marathon alone now supports thousands of events globally each year. Standardization has not prevented variety. It has given the market a foundation on which to build it.
The distance is familiar. The experience can be entirely different. Organizers can distinguish their events through the course, setting, crowd support, service, and community without asking runners to learn a new definition of a half marathon.
Triathlon offers a similar lesson. Sprint, Olympic, 70.3 and full-distance races give athletes different levels of commitment within an understood structure. There is room for different ambitions without every organizer needing to invent a new test.
Triathlon One O One tried to establish another option in 2007. Its 101-mile format combined a 1.8-mile swim, an 80.6-mile bike, and an 18.6-mile run, positioning itself between the established 70.3 and full-distance races. The inaugural event attracted a strong professional field but only about 140 athletes overall. By August, the remaining races had been canceled.
That does not prove the distance was wrong or that standardization alone explains the outcome. It does illustrate the challenge of introducing a format. A gap between existing distances is not necessarily a gap in customer demand. A new event has to give athletes a compelling reason to change their plans, training, and spending.
HYROX’s consistency is a commercial strength for the same reason. Athletes understand the test, coaches can prepare them for it, and results have a recognizable context across locations. XENOM also uses a standardized competition, while ATHX describes a set challenge across its zones. The distinction is not simply fixed format versus variety. It is what each business chooses to make consistent.
A repeatable format can also give a footwear or equipment partner a clearer product brief. But its value is broader than product development. It makes the competition easier to understand, prepare for, and return to.
That is why I would push back on the idea that variety is better for athletes and standardization is better for product. Some athletes want a different challenge. Others want another chance at the same one.
The opportunity is to create variety around a recognizable standard, not necessarily to keep changing the standard itself.
Running has built an enormous range of experiences around a handful of understood distances. Fitness racing does not need to copy that model exactly, but it would be a mistake to overlook what makes it work.
Expansion is the announcement. Repeat participation is the business.
Before treating any ambitious calendar as proof of durability, I would want answers to some fairly ordinary questions.
Can an event make money without selling every available start? Does local demand support the next market? Can the team maintain safety and delivery standards as the schedule grows? Is sponsorship strengthening a sound business or covering an event that does not work on its own?
These are not particularly glamorous questions. They are the ones that matter once the launch coverage moves on.
Rugged Maniac’s history is a useful reminder. The business attracted a controlling investment, yet the race series eventually closed. Capital validated the opportunity at one point in time. It did not guarantee permanence.
My pick is HYROX. My expectation is a more complicated outcome.
HYROX would be my choice because it has established a recognizable competition, attracted institutional capital, and built a position its founders are extending into an adjacent format. An L Catterton-led consortium acquired Infront’s majority stake, while the founders’ XENOM investment adds another relationship across the category.
That is a strong position. It is not a guarantee, and it does not mean everyone else disappears.
CrossFit’s community may endure through changes in ownership. ATHX may build a valuable business by serving athletes who want a different experience. XENOM may become complementary to HYROX rather than simply a rival.
The obstacle-racing cycle produced acquisitions, closures, and brands that continued under different owners. I would expect fitness racing to produce its own version of that outcome.
The businesses that last will need more than a distinctive format, a footwear partner, and a crowded launch event. They will need to deliver an experience people value enough to return to, at economics that make it worth delivering again.
That is the part of this race I’m watching.